
 NVDA
 MSFT
 GOOGL
 AMZN
 META

The Cheapest AI Stock Looks Expensive. The Expensive One Looks Cheap.
Five years of profit, revenue and price for Nvidia, Microsoft, Alphabet, Amazon and Meta. Three of the five trade below their own five-year average, but only Nvidia earns more than a 10-year Treasury on forward profit, Alphabet's low P/E is inflated by $99 billion of paper gains, and one session pushed Meta above its average.
We pulled five years of profit, revenue and price for Nvidia, Microsoft, Alphabet, Amazon and Meta. Three of the five trade below their own five-year average. But the stock the market fears most is the cheapest, and the one that looks cheapest is not cheap at all.
HeyTheo Research · Monday, September 21, 2026
Quick Read
The verdict: cheaper than they have been, not cheap. The five trade at 23.3 times next year's expected earnings, a 4.3% earnings yield. A 10-year Treasury pays 4.96%.
Cheapest against its own history: Nvidia, at 18.9 times forward earnings against a five-year average of 38.5. Its profit grew 12.3 times over the period; its share price grew 10 times.
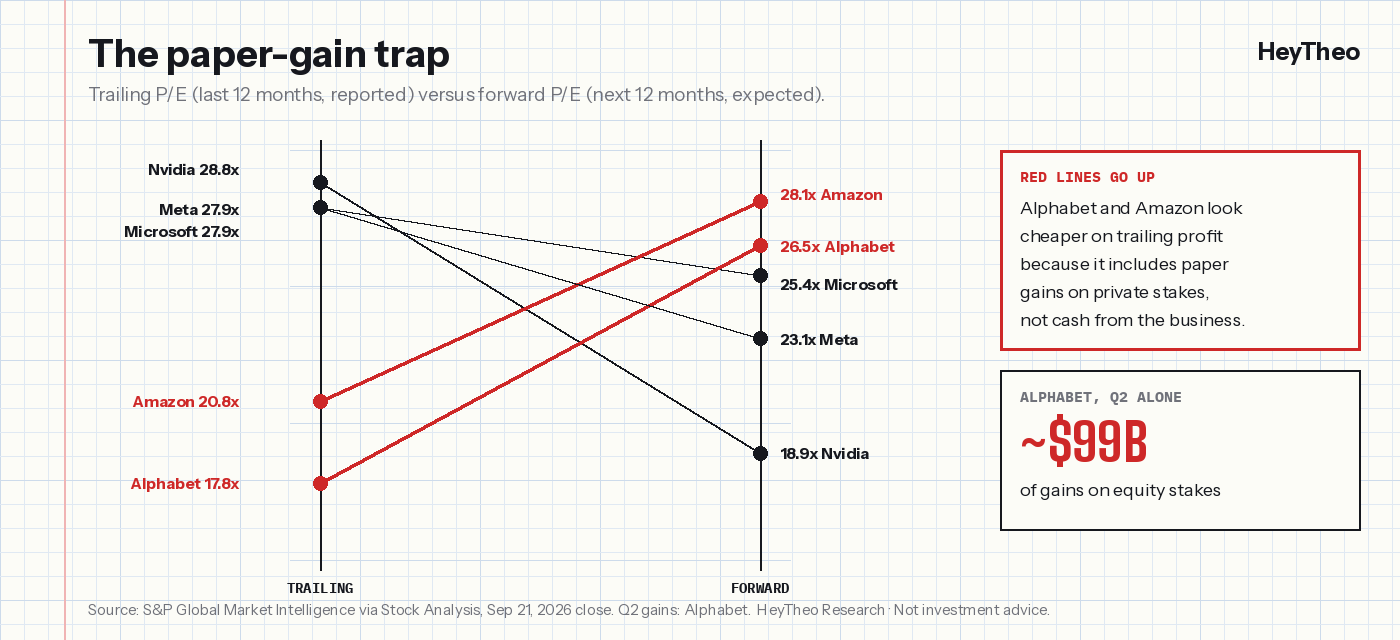
The trap: Alphabet shows the lowest trailing P/E in the group at 17.8. That number is inflated by about $99 billion of paper gains on private stakes in a single quarter. On forward earnings it trades above its own average.
What changed Monday: Meta jumped 11.4% ahead of its Connect event, which pushed it from just below its average to 6% above.
The cash gap: free cash flow yields run from 1.2% to 2.3%, and Amazon's is negative. AI spending is eating the difference between reported profit and cash.
"Is AI in a bubble?" is the wrong question. It has no answer you can act on.
The useful question is narrower: compared with their own history, and with what a risk-free bond pays today, are the five biggest AI stocks cheap or expensive?
So we pulled the numbers. Five years of revenue, profit after tax (net income) and share price for NVDA, MSFT, GOOGL, AMZN, and META, from the same data provider for all five, as of Monday's close. Every year of profit we used reconciles to what the companies themselves reported.
Here is what they show.
Company | Forward P/E today | 5-year average | Profit growth | Price growth | Free cash flow yield |
|---|---|---|---|---|---|
Nvidia | 18.9x | 38.5x | 12.3x | 10.0x | 2.3% |
Microsoft | 25.4x | 29.5x | 1.8x | 2.0x | 1.8% |
Alphabet | 26.5x | 23.5x | 1.7x | 2.5x | 1.2% |
Amazon | 28.1x | 51.8x | 2.3x | 1.6x | -0.4% |
Meta | 23.1x | 21.7x | 1.5x | 2.2x | 2.2% |
Source: S&P Global Market Intelligence via Stock Analysis, prices and multiples as of the Sep 21, 2026 close. Profit growth runs from the first to the latest full fiscal year; price growth runs from the first fiscal year-end to Sep 21. Five-year averages use fiscal year-end readings.
Forward P/E is price divided by the next 12 months of expected earnings. It is the cleaner measure here, for a reason we get to below.

1. Nvidia: the one the market fears is the cheapest
Nvidia earned $9.8 billion in the fiscal year to January 2022. In the fiscal year to January 2026 it earned $120.1 billion, and $192.9 billion over the last twelve months.
The share price rose a lot too, from $22.74 to $227.38. But profit rose faster, so the stock got cheaper as it went up.
Forward P/E has fallen from 45.5 at the start of the period to 18.9 today.
That is less than half its five-year average of 38.5.
Its forward earnings yield is 5.3%, the only one of the five above the 10-year Treasury.
The honest risk is where the profit comes from. Nvidia keeps about 64 cents of every sales dollar as profit, a record margin that depends on its biggest customers continuing to spend. That spending debate is the one we covered in our note on the AI slowdown call and the camps behind it. A low multiple on peak profit is not the same as a low multiple on normal profit.
2. Alphabet: the one that looks cheapest is not
On the most-quoted number, Alphabet looks like the bargain of the group: a trailing P/E of 17.8, the lowest of the five.
Look under it.
In the second quarter alone, Alphabet booked about $99 billion of gains on its stakes in SpaceX and a private AI company widely reported to be Anthropic. After tax, that added $77.1 billion to profit, about two-thirds of the quarter's earnings per share. None of it came from selling search ads or cloud services, and none of it was received as cash.
That is why its trailing profit of $244.1 billion is almost double its 2025 profit of $132.2 billion.
Strip it out and the picture flips:
Forward P/E, which excludes those gains, is 26.5. That is 13% above its five-year average of 23.5.
The share price rose 2.5 times over five years while core profit rose 1.7 times.
Its free cash flow yield is 1.2%, the lowest of the four that are still cash-positive, because capital spending now runs near $200 billion a year.
Paper gains can also reverse. A private company's valuation that marks up in one funding round can mark down in the next, and the same line of the income statement would then subtract instead of add.
3. Amazon: cheap on earnings, expensive on cash
Amazon has the same paper-gain issue on a smaller scale. The company said the value of its equity stakes rose $50.5 billion in the second quarter, mostly tied to Anthropic. Its trailing P/E of 20.8 is flattered; its forward P/E is 28.1.
Even so, 28.1 is far below its five-year average of 51.8, and profit grew faster than the share price (2.3 times against 1.6 times).
The catch is cash. Over the last twelve months Amazon spent $173 billion on data centers and equipment, more than the $161 billion its business brought in, leaving free cash flow about $12 billion negative. On earnings it looks cheap. On cash it has nothing left over.
Its high historical average also flatters today's discount. For much of the period Amazon's retail profits were thin, which made its P/E look enormous. Some of the "cheapening" is simply profit returning to normal.
4. Microsoft is fairly priced. Meta just got pricier.
Microsoft trades at 25.4 times forward earnings against a five-year average of 29.5. Profit and price grew roughly in step, 1.8 times and 2.0 times. It dipped to 20.7 times at the end of June and has rallied about 35% since, so most of that discount has already gone.
Meta shows how fast these readings move. Going into Monday it sat just below its average. Then the stock jumped 11.4% in a single session, on early traction for its Muse AI assistant and ahead of its Connect event on Sep 23 and 24. At the close it traded at 23.1 times forward earnings against an average of 21.7, now 6% above.
Over five years Meta's price has risen 2.2 times while profit rose 1.5 times. Monday's move bought hope about what Connect will show, not earnings that exist yet.

The bar that matters: 5%
A P/E only means something against the alternative. Flip it over and you get the earnings yield: what each dollar of share price earns.
The 10-year Treasury closed Monday at 4.96%, a touch off last week's 19-year high above 5% after the Fed's first hike since 2023, covered in last week's note. Against that:
Forward earnings yields: Nvidia 5.3%, Meta 4.3%, Microsoft 3.9%, Alphabet 3.8%, Amazon 3.6%.
Free cash flow yields: Nvidia 2.3%, Meta 2.2%, Microsoft 1.8%, Alphabet 1.2%, Amazon -0.4%.
Only one of the five earns more than a bond on next year's expected profit. None comes close on cash.
That is the gap between "cheap against their own history" and "cheap." Investors are still paying for growth that has to keep arriving. It is also why these names moved with the 10-year in our sector map: when the bond pays more, the bar goes up for everything that pays you later. Monday showed the reverse: yields eased, oil fell for a fourth day, and the Nasdaq rose 2.3%.

The rules HeyTheo tracks
Basket: group all five and watch them as one unit. When they move together, it is the rate or the AI spending story; when they split, it is company news.
Triggers: flag unusual moves on the dated events: Meta Connect (Sep 23 and 24), Microsoft and Alphabet (estimated Oct 28), Amazon (estimated Oct 29), Meta (late October) and Nvidia (late November). On report day, read capital spending first, then any gains or losses on investments.
Money flow: check whether big money is rotating between the five or leaving the group entirely.
Ask Theo: pull the bull case, bear case and what to watch on any of the five before its report.
Check the rule behind any trigger before acting on it. You trade through your own broker; HeyTheo helps you decide.
What the Price Tag Says
Cheaper than they have been is not the same as cheap. At a 4.3% earnings yield, the group earns less than a 4.96% Treasury.
Nvidia is the cheapest against its own history, on profit that sits at a record margin.
Alphabet's low trailing P/E is a paper-gain illusion. On forward earnings it sits 13% above its average.
Amazon is cheap on earnings and empty on cash.
One session moved Meta from fair to above its average. Multiples this sensitive reward checking the date on every number.
FAQs
Are AI stocks overvalued right now?
On their own history, the picture is split. Three of the five largest (Nvidia, Microsoft and Amazon) trade below their five-year average forward P/E, while Alphabet and Meta trade above. Together they earn about 4.3% of their price in expected profit, less than the 4.96% a 10-year Treasury pays, so they are not cheap in absolute terms.
Which of the big AI stocks is cheapest?
Against its own history, Nvidia: 18.9 times forward earnings versus a five-year average of 38.5, after profit grew faster than its share price. Its profit also sits at a record margin, which is the main risk to that reading.
Why does Alphabet's P/E look so low?
Its trailing earnings include about $99 billion of second-quarter gains on stakes in SpaceX and a private AI company. Those gains are not cash and can reverse. On forward earnings, which exclude them, Alphabet trades at 26.5, above its five-year average.
What is the difference between trailing and forward P/E?
Trailing P/E divides the price by the last 12 months of reported profit, including one-off gains. Forward P/E uses expected profit for the next 12 months. When one-off gains are large, forward P/E gives a truer picture.
Why compare AI stocks with Treasury yields?
Because a Treasury is the alternative with no business risk. If a stock's earnings yield is below the bond's yield, investors are paying for growth they have not yet received.
Sources
S&P Global Market Intelligence, Stock Analysis, Alphabet, Amazon, Trading Economics, CNBC, Fortune, The Motley Fool, Yahoo Finance.
Disclaimer: HeyTheo is a research and education platform, not an investment adviser or broker-dealer. Nothing here is advice to buy, sell, or hold any security. You trade through your own broker; HeyTheo helps you decide. Backtested results are hypothetical and do not guarantee future returns. References to governments, officials, or policies are for market context only and are not political endorsements. All investing involves risk, including loss of principal. Data is as of the dates noted.